Uncertainty Budget Explained: 3 Boundaries That Keep Unknown Risk Visible
An F7 explainer for supervisors and risk leaders who need to distinguish ordinary incomplete information from uncertainty that must change the work decision.

Key takeaways
- 01An uncertainty budget defines which unknowns may remain open and which must change the work decision.
- 02The three boundaries are what may remain unknown, who owns the next answer, and what protects the work while the gap is open.
- 03Risk competence means noticing hazards even when familiar work looks normal, which makes unresolved assumptions easier to challenge.
- 04The budget is exceeded when the unknown could change exposure, the interim control cannot be verified, or the next step creates an irreversible consequence.
Risk decisions rarely fail because nobody noticed uncertainty. They fail because uncertainty was treated as a temporary inconvenience instead of a condition that needed a boundary, an owner, and a response.
An uncertainty budget is the defined amount and type of unknown information that a team may carry while planning or performing work. It makes uncertainty visible, assigns a limit to what can remain unresolved, and states what evidence or protection is required before the task continues.
What does an uncertainty budget mean in risk management?
An uncertainty budget is not permission to accept unknown risk. It is a decision aid that separates ordinary incompleteness from uncertainty that could change the hazard, exposure, or effectiveness of a control.
For example, a supervisor may not know the exact condition behind a recurring equipment alarm. The uncertainty budget asks whether that gap can remain open during a controlled inspection, or whether the team must isolate the equipment, obtain better evidence, or stop the task before exposure increases.
OSHA describes safety management as a process that identifies hazards, controls them, and verifies that protections remain effective. NIOSH explains the hierarchy of controls, which helps teams select protections according to the hazard and the way exposure is reduced. ISO 31000 describes a structured risk-management process that connects identification, treatment, monitoring, and communication. Those principles support an uncertainty budget because the unresolved question has to be connected to a real exposure and a real control.
3 boundaries that keep unknown risk visible
Boundary 1: What may remain unknown?
Some unknowns concern convenience, such as an incomplete description that does not alter the work. Others concern consequence, such as whether stored energy has been released, whether a temporary guard is adequate, or whether a rescue route remains open.
Write the unresolved question in operational language. “The condition is being reviewed” hides the issue. “The isolation point has not yet been independently verified” names the gap that must influence the next decision.
This boundary protects the team from treating all missing information as equally harmless. It also gives the supervisor a practical test for escalation, because the question can be compared with the consequence of being wrong.
Boundary 2: Who owns the next answer?
An uncertainty budget becomes weak when everyone agrees that more information is needed but nobody owns the work of obtaining it. Name the person who can authorize the next step, the function that must provide technical evidence, and the person who confirms that the answer is usable in the field.
Andreza Araujo's risk-management grounding makes the same distinction in *Sorte ou Capacidade*, whose central position is that risk should be managed with method rather than treated as a test of courage or luck. Ownership turns that principle into a visible operating practice.
Boundary 3: What protects the work while the gap is open?
The interim response should match the possible consequence. It may involve a narrower scope, additional verification, a competent person at the worksite, physical isolation, a changed sequence, or postponement until the evidence is available.
A Headline Podcast conversation describes risk competence as the readiness to recognize a hazard even when the situation looks normal. That insight matters here because familiar work often encourages teams to spend uncertainty without noticing that the conditions have changed.
How can a supervisor differentiate acceptable uncertainty from dangerous uncertainty?
| Question | Uncertainty that may remain open | Uncertainty that requires action |
|---|---|---|
| Could the answer change the hazard? | No material change to exposure or control | It could introduce energy, access, movement, pressure, or a new person at risk |
| Can the work be protected meanwhile? | A defined interim control is verified | The interim control is assumed, incomplete, or impossible to check |
| Is the answer due before the next decision? | The work can pause safely while the question is resolved | The next step would commit the team to an irreversible or higher-exposure condition |
The table is not a substitute for a risk assessment. It is a short decision screen that helps a supervisor avoid two opposite errors, stopping every task because some detail is missing and allowing a critical unknown to travel silently into execution.
For a related distinction, compare an honest pre-task uncertainty review with the broader question of when an escalation threshold has been reached. The first clarifies the gap. The second defines the response.
When should an uncertainty budget be used?
Use one before non-routine work, during a temporary change, after a process upset, when a contractor takes over an unfamiliar task, or whenever a control is being accepted on the basis of assumption rather than evidence. The method is especially useful when production pressure makes delay feel more costly than incomplete information.
Start with one question that could change the decision. Name the owner, set the boundary, record the interim protection, and define the evidence that closes the gap. If the answer cannot be verified before the next exposure, the budget has been exceeded.
That final test keeps the concept practical. An uncertainty budget is not a spreadsheet score and not a softer name for risk acceptance. It is a visible limit that helps leaders decide when the organization knows enough to proceed, when it needs protection while learning, and when unresolved uncertainty has become the risk.
For more conversations and practical analysis on risk decisions, safety leadership, and workplace culture, explore the Headline Podcast.
Frequently asked questions
What is an uncertainty budget in safety management?
Is an uncertainty budget the same as accepting risk?
Who should own an uncertainty budget?
When should a supervisor exceed the uncertainty budget?
About the author
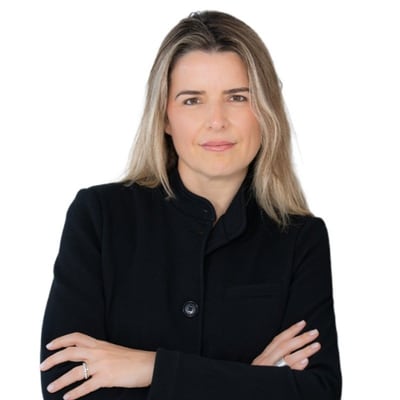
Andreza Araújo
Safety Culture Expert | Senior EHS Executive
Andreza Araújo is a safety culture expert and senior EHS executive with more than 25 years of experience in environment, health and safety. She is a Civil Engineer and Occupational Safety Engineer from Unicamp, holds a Master's degree in Environmental Diplomacy from the University of Geneva, and completed sustainability studies at IMD Switzerland. Andreza has served in Global Head of EHS roles in Fortune 500 environments, leading cultural transformation programs across multinational operations. She has represented Brazil as a speaker at the United Nations in Paris and has spoken at the International Labour Organization in Turin. She is the author of more than 16 books on safety culture in Portuguese, Spanish, English and German. Her work has earned more than 10 EHS awards, including two recognitions from Indra Nooyi, former PepsiCo CEO.
- Civil & Safety Engineer (Unicamp)
- M.A. Environmental Diplomacy (University of Geneva)
- Sustainability Cert (IMD Switzerland)
- People Management & Coaching (Ohio University)
- UN Paris speaker representative for Brazil
- ILO Turin speaker
- LinkedIn Top Voice
- Indra Nooyi PepsiCo CEO recognition (2x)
Documentaries
Watch Andreza's documentaries
Three productions on safety culture, organizational failure and the human lessons behind major disasters.
Podcasts
Listen to Andreza's podcasts
She hosts three shows on safety leadership, EHS and organizational culture, in English and Portuguese.